THOUGHT LEADERSHIP FEATURE
Southern Africa is well endowed with a number of the critical minerals that are becoming increasingly important as the global automotive industry transitions towards new energy vehicles (NEVs) and other clean-energy technologies. However, despite this resource advantage, much of the region’s participation in global mineral value chains has historically remained concentrated around the extraction and export of raw or minimally processed materials.
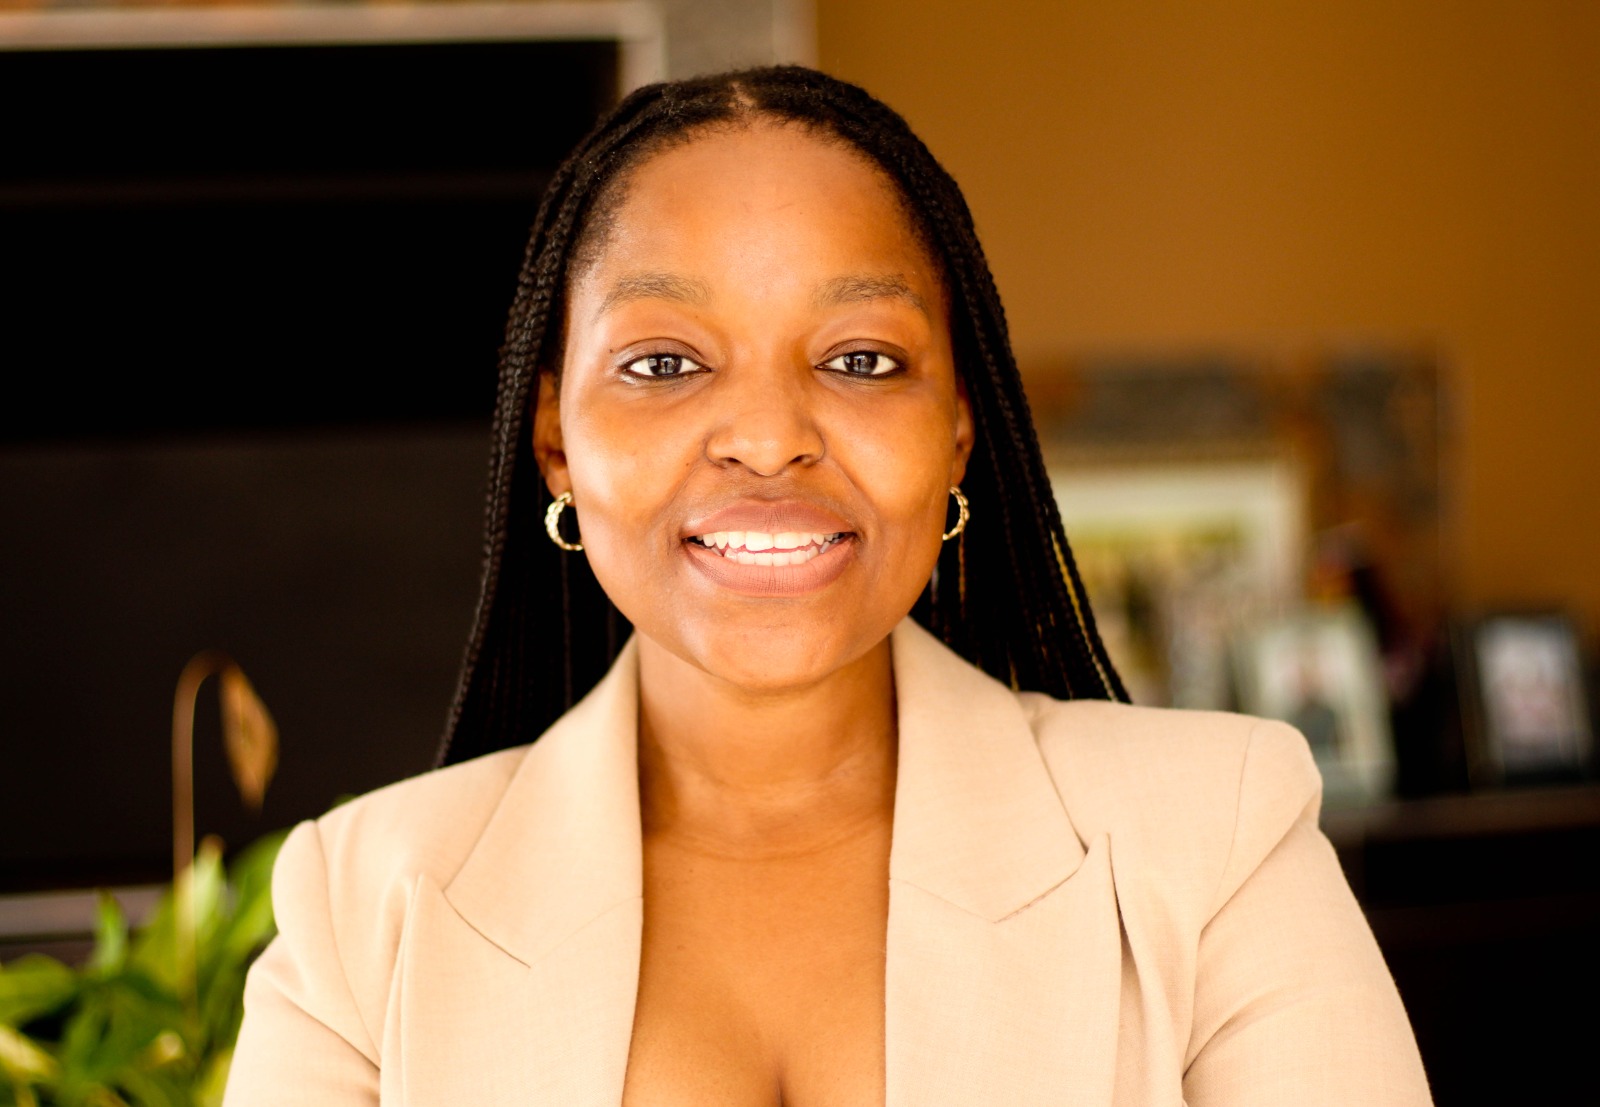
By Ziphozakhe Miti – Manager: Automotive & Advanced Manufacturing
This raises an important question: if Southern Africa has many of the minerals required to support the future of mobility, should our participation in this growing value chain end at extraction?
The transition towards NEVs provides an opportunity for us to look at this differently. We can move beyond being predominantly exporters of critical minerals and consider how these resources can increasingly support beneficiation, value addition and ultimately greater participation in the manufacturing activities associated with the growing NEV ecosystem.
This conversation is particularly relevant given the increasing global demand for minerals such as manganese, lithium, cobalt, graphite, nickel, copper and rare earth elements, which have applications across batteries, electric vehicles, energy storage and other emerging technologies. South Africa’s Critical Minerals and Metals Strategy recognises this opportunity and places greater emphasis on value addition, localisation and the development of domestic beneficiation capabilities.
What is also encouraging is that this conversation is increasingly finding its way into automotive industrial policy.
The proposed amendments to the Automotive Production and Development Programme Phase 2 (APDP2), published in May and June 2026, seek to recognise additional minerals and materials associated with electric vehicle battery production within the automotive incentive framework. The proposals also provide for qualifying battery minerals sourced from the Southern African Development Community (SADC) region. This creates an opportunity to strengthen the link between regional critical-mineral resources, beneficiation and South Africa’s established automotive manufacturing capabilities.
For me, this is where the opportunity becomes particularly interesting.
The beneficiation of Africa’s mineral resources is certainly not a new conversation. However, the transition towards NEVs gives us an opportunity to connect this long-standing beneficiation ambition to a global value chain that is rapidly developing. The conversation therefore needs to move beyond what we extract and towards what we can do with what we extract.
Of course, having the mineral resources does not automatically translate into an industrial advantage. Beneficiation and downstream manufacturing require appropriate infrastructure, reliable and competitively priced energy, technology, skills, investment, logistics and access to markets. These are important considerations if the region is to move into higher-value areas of the value chain.
This also requires clear choices about where the region can compete. Different stages of the NEV value chain require different capabilities, and investment should be guided by commercial viability, customer requirements and opportunities to build on existing industrial strengths.
So, where do Special Economic Zones fit into this?
SEZs can play an important role in creating the enabling environment required to support this transition. Through established industrial infrastructure, investment facilitation, logistics connectivity, applicable incentives and access to manufacturing ecosystems, SEZs provide platforms through which beneficiation and downstream manufacturing opportunities can be supported and ultimately connected to regional and global markets.
For the East London Industrial Development Zone (ELIDZ), this opportunity is particularly relevant given its established position within South Africa’s automotive manufacturing sector.
The ELIDZ already has an established automotive and manufacturing base, supported by purpose-built industrial infrastructure, investment facilitation capabilities and connectivity to key logistics gateways. As the automotive industry continues to transition towards NEVs and other emerging technologies, this provides a platform from which the ELIDZ can continue to explore and pursue higher-value investment opportunities associated with the changing automotive value chain.
For the ELIDZ, potential opportunities include battery pack assembly, electric vehicle components and support for existing suppliers adapting to new manufacturing requirements, subject to commercial and technical feasibility.
There is also a broader regional opportunity that should not be overlooked.
Greater integration between Southern Africa’s mineral-producing economies, beneficiation capabilities and established manufacturing locations could support the development of stronger regional value chains. This creates an opportunity for the region to begin looking at its critical-mineral endowment not only as an extractive advantage, but increasingly as an industrialisation advantage.
Such integration should also create opportunities for local suppliers, skills development and employment, so that greater regional participation translates into benefits for businesses and communities.
Moving from mine to mobility will require stronger alignment between mineral, automotive, trade and industrial development policy. It will also require greater regional cooperation and deliberate investment into the capabilities required to beneficiate, manufacture and participate in higher-value areas of the NEV value chain.
The next step is to translate these ambitions into viable investment projects, supported by partnerships between mineral producers, manufacturers, technology providers and financiers.
A critical part of this work is securing manufacturers and buyers for what the region intends to produce. Stronger links with vehicle manufacturers and battery producers would help ensure that beneficiation investments respond to actual demand and meet the standards required to enter automotive supply chains.
For the ELIDZ, the opportunity is to continue positioning itself within this changing landscape and to leverage its existing automotive and advanced manufacturing capabilities to support and attract the next generation of industrial investment.
Southern Africa already has an important part of what the future of mobility requires beneath its soil. The opportunity before us is to ensure that more of these are processed within the region, used in regional manufacturing and translated into lasting economic value.
Our participation in the future of mobility should therefore not only be about the minerals we supply, but increasingly about what we are able to build from them.
For media enquiries:
Mr Siphosethu Tikana
Acting Manager: Marketing & Corporate Communications
Email: siphosethuti@elidz.co.za
Tel: 064 900 8392 / 076 800 5317